Key Points
-
Interested in Affirm Holdings, Inc.? Here are five stocks we like better.
-
Affirm reported strong earnings with 35% revenue growth, yet shares still fell about 8% in after-hours trading.
-
DraftKings grew revenue 16% year-over-year and payers 13%, but trimmed guidance and posted wider losses amid a 46% year-to-date stock decline.
-
The Vanguard Mid-Cap ETF offers a diversified, low-fee alternative that has outperformed both individual stocks, with a 12.6% year-to-date return.
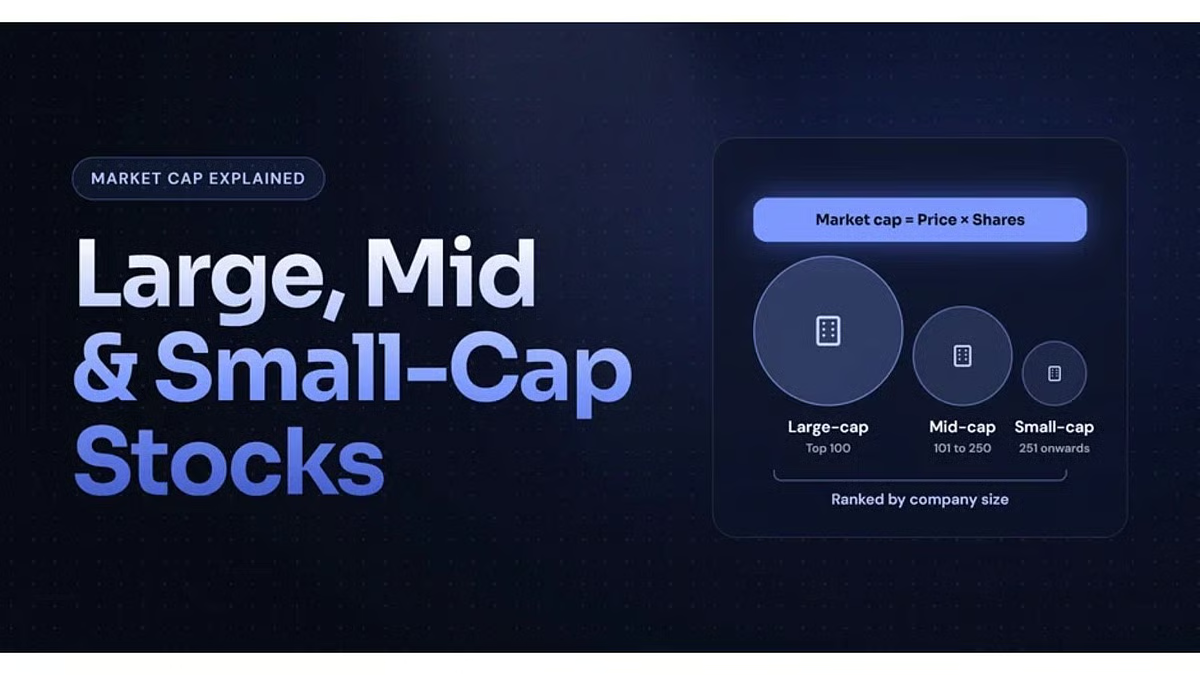
As the AI sell-off continues to challenge many of the gains that the tech sector made throughout the year, investors may be looking for opportunities outside of that space—and even beyond large- or mega-cap names entirely.
Top mid-cap growth names like Affirm Holdings Inc. (NASDAQ: AFRM) and DraftKings Inc. (NASDAQ: DKNG) stand out not only for their individual performance but also for their roles in two industries that are capitalizing on changing consumer habits.
→ The Ugly Truth Behind SoundHound’s Q3 Results
Both companies reported their latest earnings on Nov. 5, 2026, strong growth but also challenges that could weigh on their stocks. For investors willing to tolerate volatility, the question is whether their longer-term growth potential outweighs those risks.
Affirm: Buy-Now-Pay-Later Business Delivers 34% Growth
Affirm is a fintech firm providing a buy-now-pay-later (BNPL) platform with flexible payment options for customers.
→ Lemonade’s Revenue Soars 73%—So Why Did Its Stock Turn Sour After Earnings?
Amid inflation and consumer affordability concerns, BNPL platforms have grown in popularity. A 2026 J.D. Power survey found that more than 37% of American consumers had utilized BNPL services within a 90-day period.
Affirm’s Q1 fiscal 2027 earnings results reflect this mounting engagement.
→ Anthropic’s S-1 Strengthens the Case for Broadcom’s AI Growth
The company saw 34% year-over-year (YOY) gross merchandise volume (GMV) growth. The company established a full-fiscal-year floor of at least 30% growth in this area as well. At the same time, revenue climbed by 35% YOY to $1.26 billion, beating the analyst estimate of approximately $1.21 billion. Earnings per share (EPS) came in more than nine cents above the analysts’ expectations.
Still, the market responded by sending AFRM shares down by around 8% in after-hours trading following the report.
This suggests that, despite strong financial performance and broad support from Wall Street analysts, an earnings win does not necessarily equal immediate price appreciation. On the other hand, this may be an opportunity to enter a position in AFRM at a discount, if it’s growth trajectory remains steady.
DraftKings: Predictions Bet Adds Opportunity—and Execution Risk
Sports betting is a rapidly growing market made possible by changes to regulations, mobile accessibility, and increased customer interest. DraftKings is already one of the leading companies in the industry and has also recently launched a prediction market to capitalize on a related and very popular trend.
While building out the predictions platform will continue to take significant capital and time, DraftKings’ core operations demonstrate their value and growth potential based on their current status thanks to the firm’s Q3 2026 earnings.
Revenue increased by more than 16% YOY, though losses per share came in wider than analysts had predicted. Still, sports revenue leads the way with robust growth of 31.5% YOY, and monthly unique payers also increased by 13% over the same period. This last metric in particular highlights that DraftKings may still have room to grow its customer base by a considerable margin.
The question for the company will be how to translate that engagement into more revenue—average revenue per monthly unique payer increased by only 3% last quarter—and, crucially, into sustained profitability.
DraftKings’ Predictions platform may be just the missing piece to make this possible. However, it will take time to scale further, and investors will likely still have to contend with uncertainties regarding costs, performance, and profitability in the meantime.
Execution risk may overshadow potential for some, although, like Affirm, Wall Street is quite bullish overall on DKNG stock.
Critically, DraftKings also trimmed its guidance in the latest earnings report, a move that is not likely to help address its share price drop of 46% year-to-date (YTD) in the near term.
Vanguard Mid-Cap ETF: A Lower-Risk Alternative
An alternative approach for investors seeing the growth potential in mid-caps more generally but not willing to accept the risk of either of the two companies above is a broader exchange-traded fund like the Vanguard Mid-Cap ETF (NYSEARCA: VO).
With a return of 12.6% YTD, this fund has solidly outperformed both of the individual stocks above in 2026.
VO’s 279 holdings are available for an annual fee of 0.03%, which is quite low even among the slate of low-cost, broad-based ETFs increasingly common in the space.
The breadth of VO’s portfolio, including the fact that no single position represents more than about 1% of the basket, may provide some of the growth potential of individual companies like the ones above while also mitigating the individual stock risk, giving some less-risk-tolerant investors an opportunity to aim for both goals in a single investment.
The article “Are These 2 Mid-Cap Growth Stocks Worth the Risk?” was originally published by MarketBeat.
View MarketBeat’s top stocks for November 2026.