Introduction
The French 10-year interest rate on October 2 was 4.90%, an increase of approximately +101bp from 3.89% on July 16.
The term ‘approximately’ is used for figures that have been calculated and rounded. All times are in Japan Standard Time.
5-line summary
Government bonds (OATs, etc.) issued by the AFT are denominated in euros, and it is financial institutions that hold a large amount of foreign currency-denominated debt securities.
-
The 10-year interest rate is approximately +101bp, from 3.89% on July 16 to 4.90% on October 2.
-
AFT government bonds (OATs, etc.) are only denominated in euros, and foreign currency-denominated debt securities in the government sector are 2.4%.
-
Foreign currency-denominated debt securities for financial institutions are 21.7%, and dollar-denominated liabilities of banks are 2.158 trillion dollars.
-
The FRB swap balance is 207 million dollars as of September 30.
-
The ratio of dollar-denominated liabilities for banks at the end of 2009 was approximately 27.5% for Greece and approximately 29.6% for France.
Terms to know in advance
I will briefly confirm the terms used in this article first.
-
bp: Refers to 0.01 percentage points.
-
AFT and TEC10: AFT is the Agence France Trésor, and TEC10 is the 10-year benchmark yield published by the AFT.
-
Debt securities and foreign currency-denominated: Debt securities refer to bonds, and foreign currency-denominated refers to being denominated in currencies other than the euro.
-
Government sector: In the classification of the Bank for International Settlements (BIS), this is the general government, which combines the central government, government agencies, local governments, and social security funds.
-
MMF: An investment trust that manages investors’ money in short-term bonds, etc.
-
Swap: An arrangement where central banks exchange currencies and return them on a specified date at the same rate.
10-year interest rate at 4.90%, approximately +101bp from 3.89% on July 16
The TEC10 on October 2 is 4.90%. The previous figure on July 16 was 3.89%.
Calculating from AFT data, the difference is approximately +101bp.
According to a Reuters report citing La Tribune, Moody’s stated on October 2 that the passage of the 2027 budget is “highly uncertain.”
The credit rating is Aa3 with a negative outlook from Moody’s.
AFT government bonds are only euro-denominated, while foreign currency debt securities of the government sector are 2.4%.
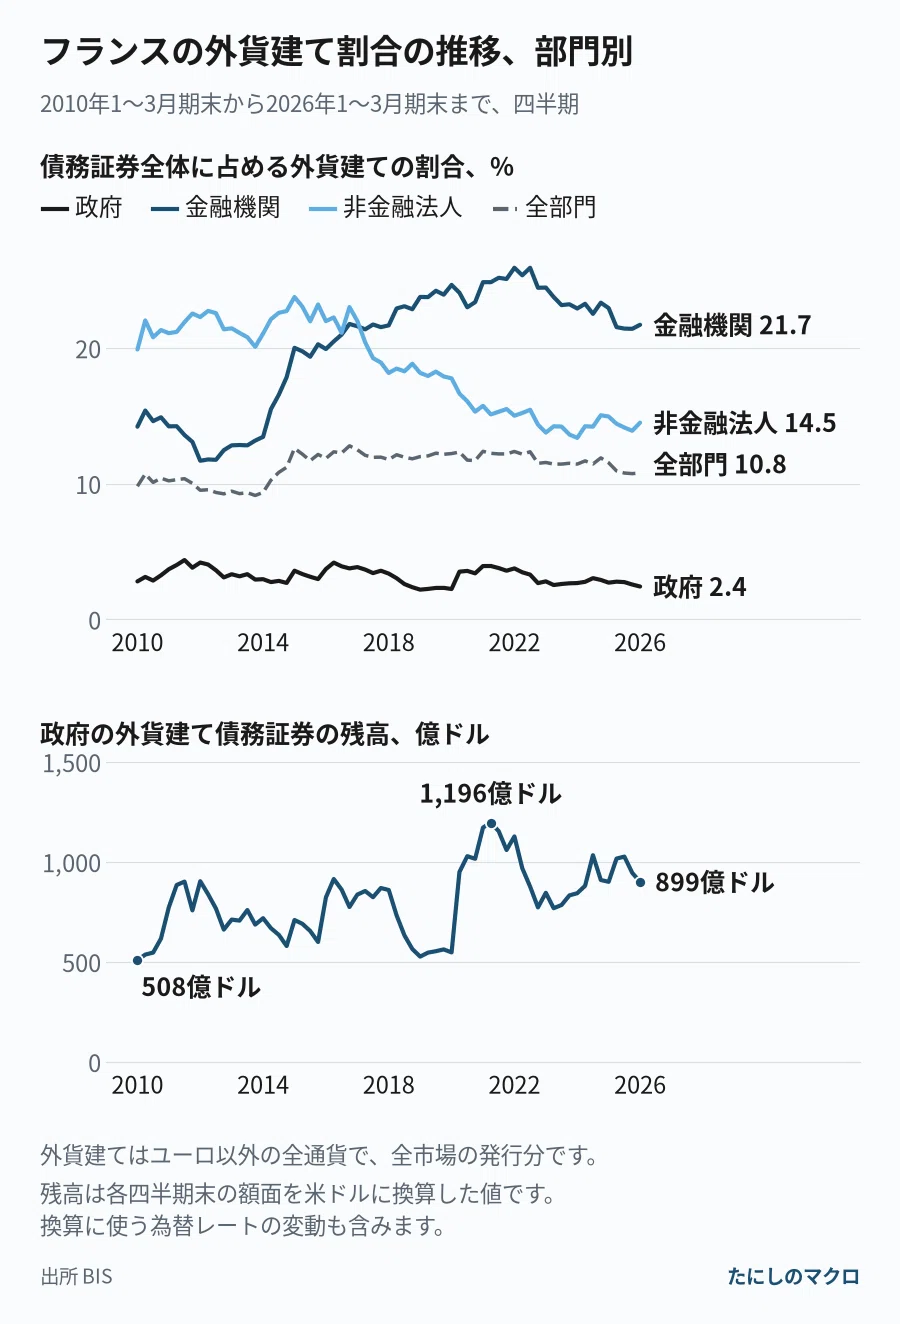
As of the end of the January-March 2026 quarter, foreign currency debt securities of the government sector stood at 2.4%. The figure was 2.6% at the end of the previous October-December 2025 quarter.
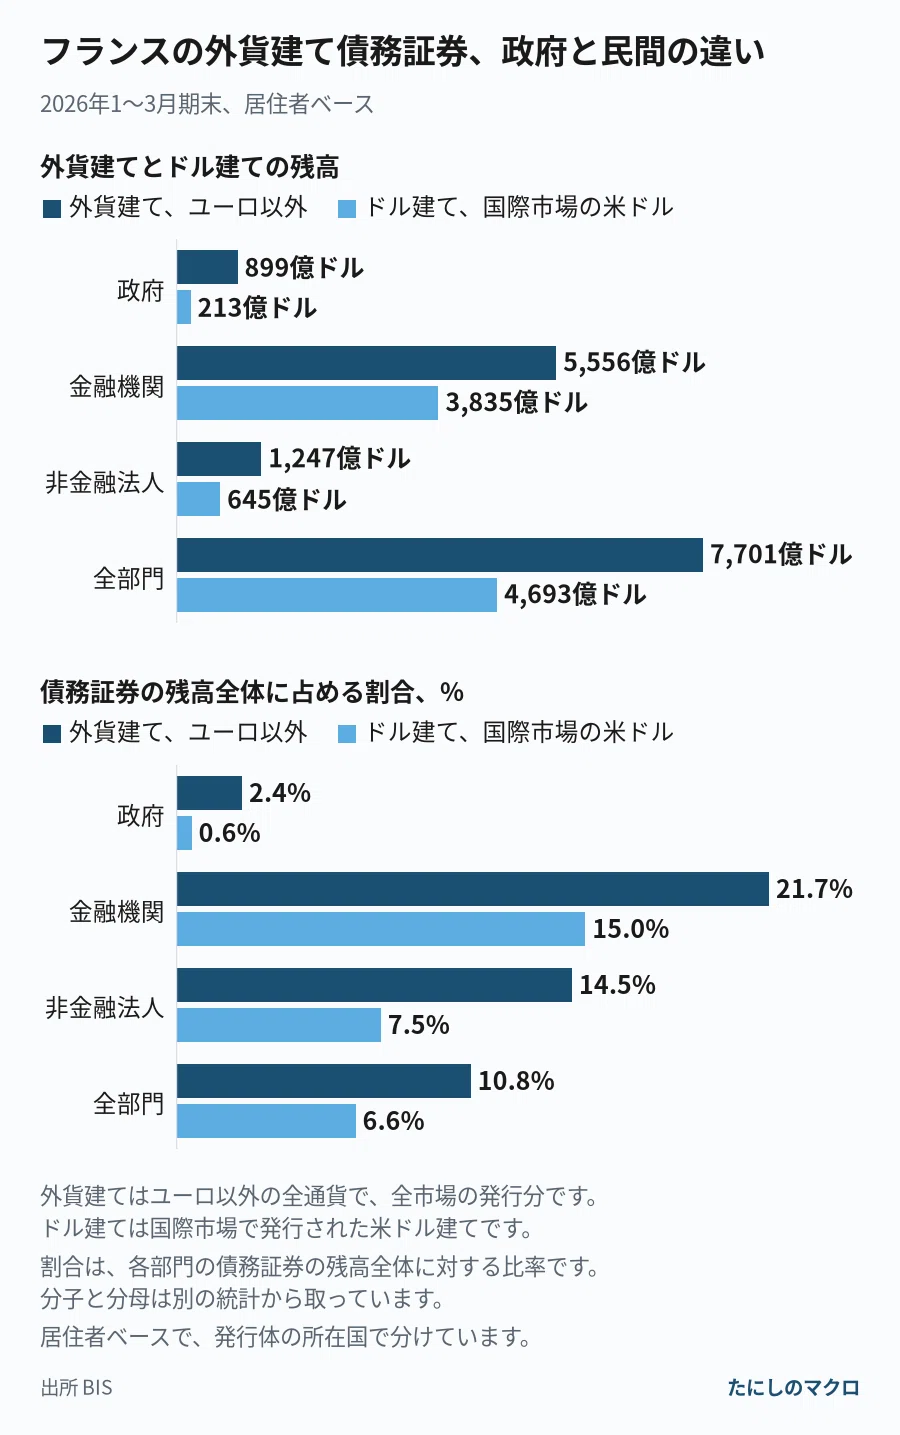
Government bonds (OATs, etc.) issued by the AFT are only euro-denominated. Sources are the AFT 2024 Activity Report and the Court of Audit.
According to BIS data, out of approximately $89.9 billion in foreign currency debt, the central government (which includes national agencies under the BIS classification) accounts for about $5.5 billion, with the remaining approximately $84.3 billion held by entities other than the central government (local governments and social security institutions).
Foreign currency debt securities of financial institutions are 21.7%.
As of the end of the January-March 2026 quarter, foreign currency debt securities of financial institutions stood at 21.7%. The peak since 2010 was 25.9% at the end of the January-March 2022 quarter.
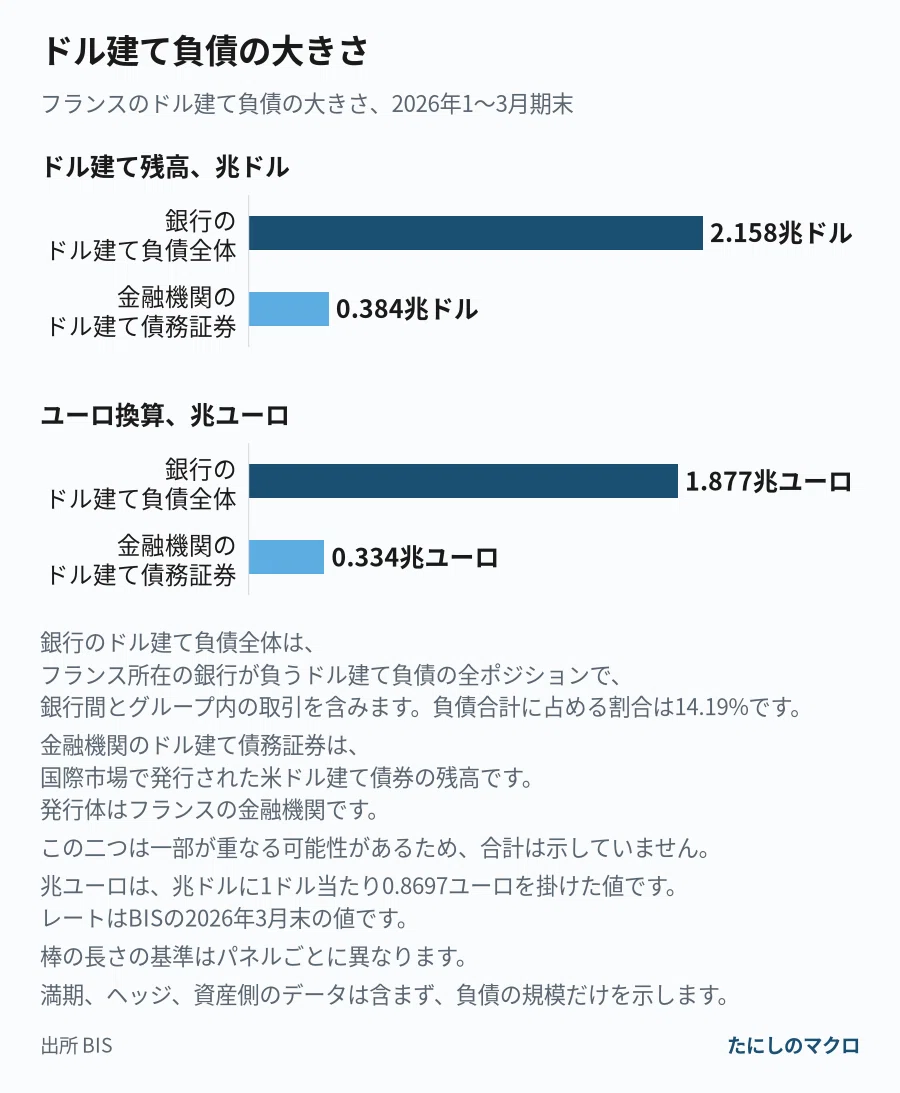
Bank dollar-denominated liabilities are $2.158 trillion, a channel for funds from US MMFs.
As of the end of the January-March 2026 quarter, dollar-denominated liabilities of banks located in France stood at $2.158 trillion. The figure was $2.068 trillion at the end of the previous October-December 2025 quarter.
According to data from the US Office of Financial Research (OFR), funds provided by US prime MMFs to French issuers and repo counterparties reached $103.9 billion at the end of August, up from $99.9 billion at the end of July.
According to BIS and ECB documents, banks operate by borrowing dollars on a short-term basis, and if they are unable to refinance, they are expected to try to secure dollars by selling dollar-denominated assets or reducing lending.
During the Eurozone debt crisis in 2011, according to the ECB, the balance of US MMFs held in European issuers fell by 9% month-on-month in October, and was down 42% compared to May 2011.
I view the banks, not the countries, as the ones in danger, assuming the ECB will intervene in euro-denominated debt.
The Fed’s standing swap facility involves 5 central banks, with a balance of $207 million as of September 30.
The Fed’s swap balance on September 30 was $207 million. This was an increase of $135 million from the previous week.
The Fed’s standing swap facility involves five central banks: Canada, the UK, Japan, the ECB, and Switzerland, and has no set expiration date.
The mechanism works by the Fed providing dollars to the ECB and others, and the ECB taking collateral to lend to banks within its jurisdiction. The swap began on December 12, 2007, and became a standing facility on October 31, 2013. The maximum balance was $583.1 billion on December 17, 2008.
According to a Reuters report on August 30, 2026, European central bank officials stated that while Fed authorities promised to honor all commitments, they could not guarantee against sudden policy shifts by President Trump.
The same report also conveys that while some stakeholders are concerned about political intervention in swap lines, they expect no changes.
Comparison with Greece in 2009, bank dollar-denominated liabilities are about 27.5% and about 29.6%
The fiscal balance to GDP ratio was -15.4% for Greece in 2009 and -5.1% for France in 2025. The ratio of bank dollar-denominated liabilities was higher for France at about 29.6% at the end of 2009.
The Greek crisis is a phase where the interest rate spread with Germany widened and the FRB resumed expired swaps in May 2010 due to tensions in European dollar funding, so we compare it with France. The figures for fiscal balance, current account balance, and interest rate spread with Germany differ for France from those of Greece at the time.
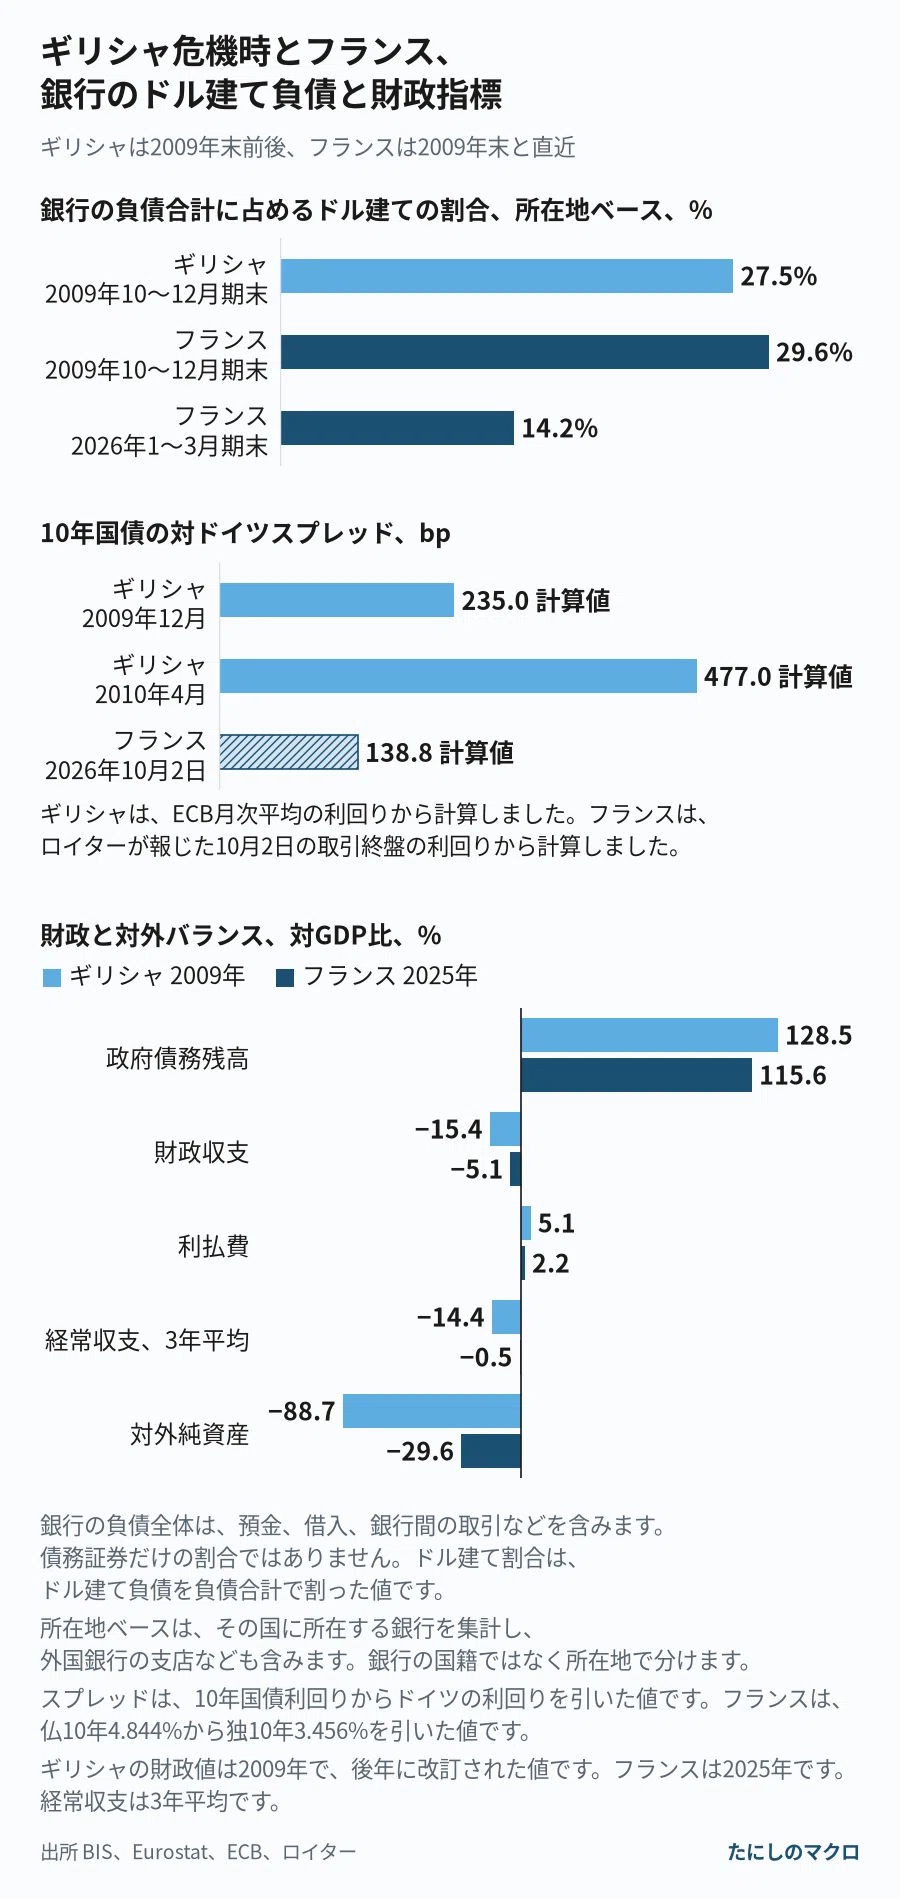
The 3-year average of the current account balance (2007-2009 for Greece, 2023-2025 for France) is -14.4% for Greece and -0.5% for France.
According to ECB data, the interest rate spread with Germany was about 235bp in December 2009 and about 477bp in April 2010 for Greece. For France, it is about 138.8bp based on the yield at the end of trading on October 2 reported by Reuters.
According to BIS locational banking statistics, the proportion of dollar-denominated liabilities in total bank liabilities was about 27.5% for Greece and about 29.6% for France at the end of the October-December 2009 quarter, with France having the higher figure. The figure for France at the end of the January-March 2026 quarter is about 14.2%.
What to watch next
Dates that are set include Moody’s review on October 23 and the maturity of the swap for the ECB on October 8.
-
Moody’s review on October 23: How Aa3 and negative will be handled
-
Next published value of TEC10: How 4.90% will move
-
FRB swap balance: How the September 30 balance of $207 million will move in weekly statistics. Separately, the 7-day $207 million for the ECB traded on September 30 matures on October 8
-
Bank dollar funding: How the next BIS statistic of $2.158 trillion and the next OFR monthly figure of $103.9 billion will move
Summary
The French 10-year yield is 4.90%, government bonds (OATs, etc.) issued by the AFT are euro-denominated, and foreign currency debt securities for financial institutions are 21.7%.
-
AFT government bonds (OATs, etc.) are only euro-denominated, and BIS foreign currency debt securities for the government sector are 2.4%
-
Bank dollar-denominated liabilities are $2.158 trillion, and the FRB swap balance is $207 million
-
The ratio of bank dollar-denominated liabilities at the end of 2009 was about 27.5% for Greece and about 29.6% for France
Related links
These are related articles.
https://tanishi-macro.hatenablog.com/entry/france-10y-yield-banks-usd-2026-10